Where do you want to start?
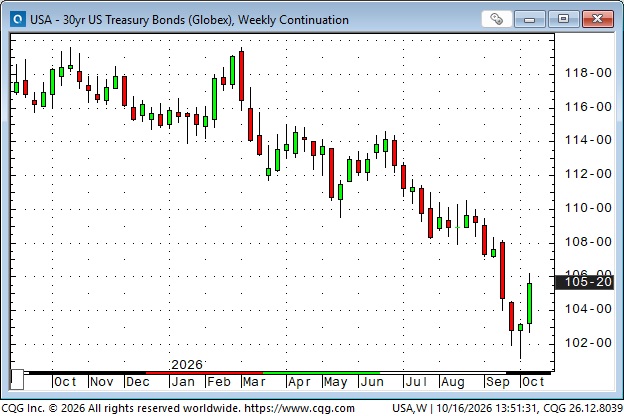
The 30-year bond futures fell relentlessly from late June to last week’s lows, down 13 full points, while cash-market yields soared to ~5.67%, the highest in twenty-something years.
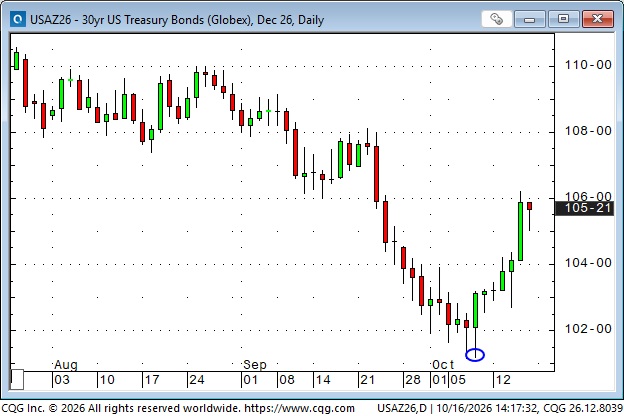
But the bond market turned higher last Thursday (blue ellipse below), closed the week at the highs, then rallied more on Monday and Tuesday ahead of Wednesday’s CPI report. The CPI report was “hotter than expected,” and the market initially tanked, taking out Monday’s and Tuesday’s lows, but it came roaring back and traded above Tuesday’s highs. Thursday’s PPI report was also “hotter than expected,” but the rally accelerated, and we closed the week 5 points above last week’s lows.
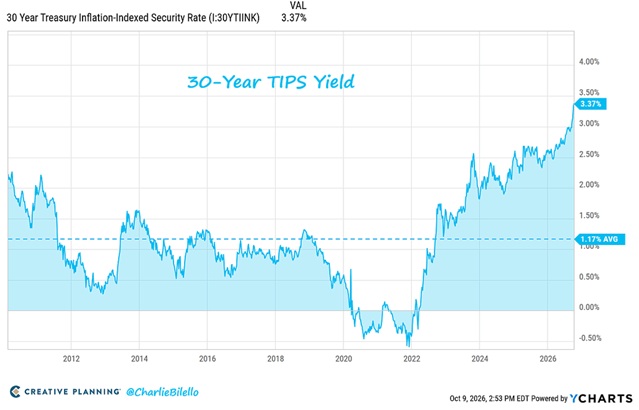
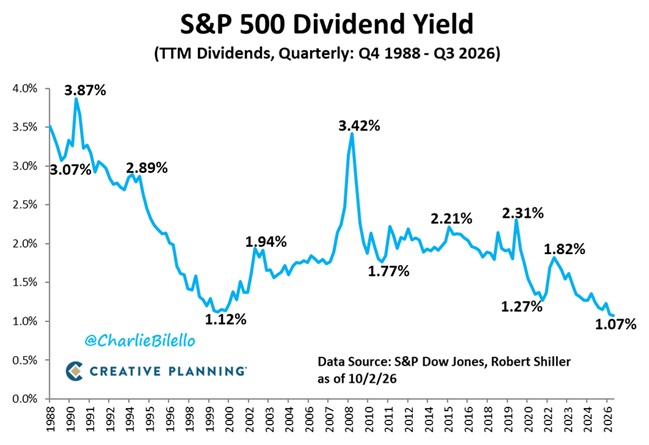
Why the huge “counterintuitive” bond market rally despite “hotter than expected” inflation reports? My first guess: short-covering. Everybody and his dog was short bonds. The doomsayers were in high dudgeon about fiscal deficits and runaway inflation. Trend followers were probably maxed out short. Second guess: “rate-sensitive” buyers were nibbling with yields north of 5% (last week’s Treasury auctions were strong). Third guess: Real Money accounts were hedging/rebalancing away from stocks and into bonds. (Treasury yields at 5% versus a 1% S&P dividend yield, and real yields at twenty-something-year highs).
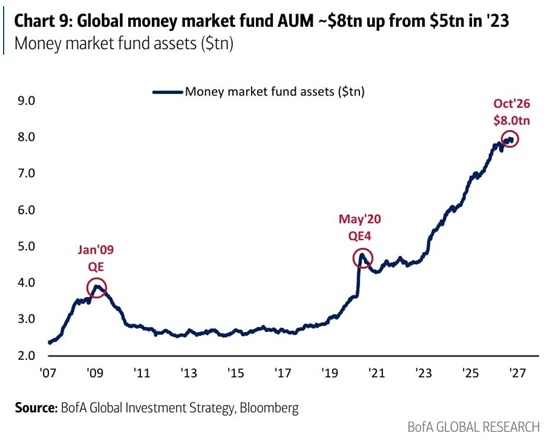
Capital flows into money market funds may also signal that some people are OK with staying out of the stock market.
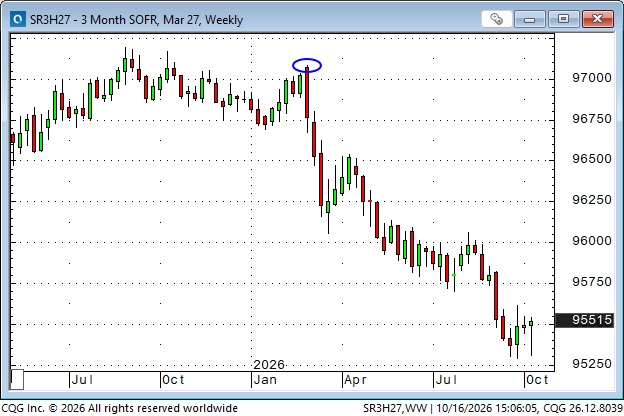
Expectations for short-term interest rates (STIR) have risen since the war with Iran started (blue ellipse), but have steadied over the past couple of weeks. This is a chart of the March 2027 Secured Overnight Funding Rate (SOFR).
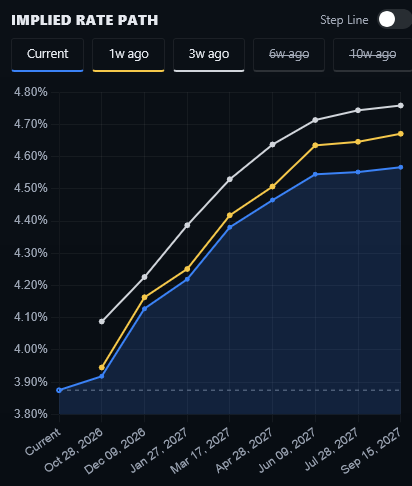
The forward market is pricing only a 17% chance of the FOMC raising rates at the October 28 meeting and an 84% chance of a 25bps increase at the December 9 meeting. This chart is from rateprobability.com.
Currencies
The DXY US Dollar Index surged to a 19-month high after Wednesday morning’s CPI report but couldn’t sustain the gains. Friday’s close was October’s lowest daily close.
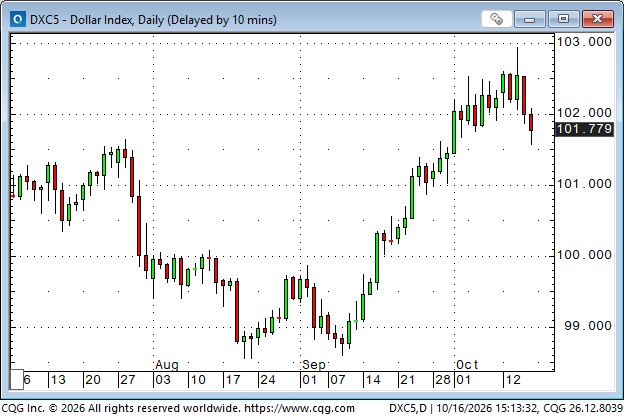
Why the USD reversal this week? My first guess: USD bulls took profits. COT data as of October 6 shows a sharp increase in net speculative short positions in currency futures over the last 6 weeks, with Euro and British Pound shorts at a 5-year high. (The October 13 COT data was just released; net speculative short currency positioning increased from the week before – no surprise!)
The USD has benefited from widening interest rate differentials, a soaring equity market, and “energy independence.”
Equities
Several leading stock market indices, including the S&P, Nasdaq, Russell 2000, DJIA, Dow Jones World Index, Euro Stoxx 50, the UK Footsie and the TSE, reached record highs in August, but since then they have gone in different directions.
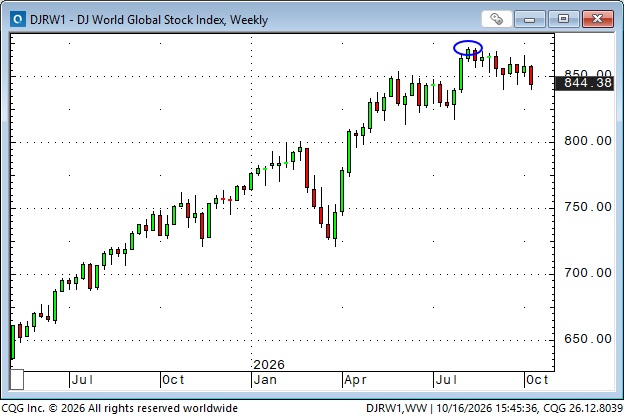
The Nasdaq made a (lower) high in mid-August along with several other indices, then drifted lower into mid-September before rallying to a record high in early October – on the back of surging tech (AI) shares. The Nasdaq has dropped sharply from last week’s record highs as “questions” about AI (and semiconductors and memory and financing) have surfaced.
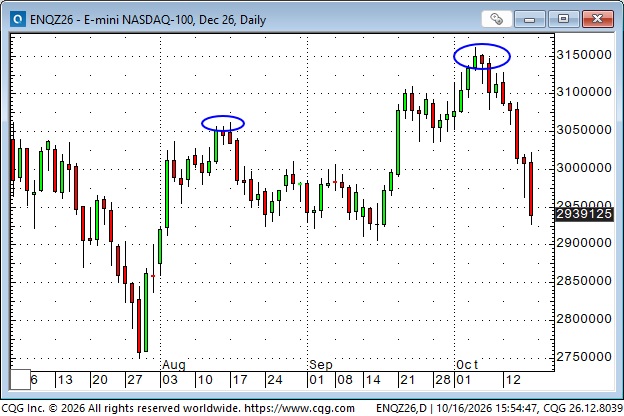
The Russell 2000 reached a record high in mid-August, then trended steadily lower. This week’s close was the lowest weekly close since April, down ~12% from the mid-August highs. There was no “rotation” of capital out of Nasdaq stocks and into Russell stocks.
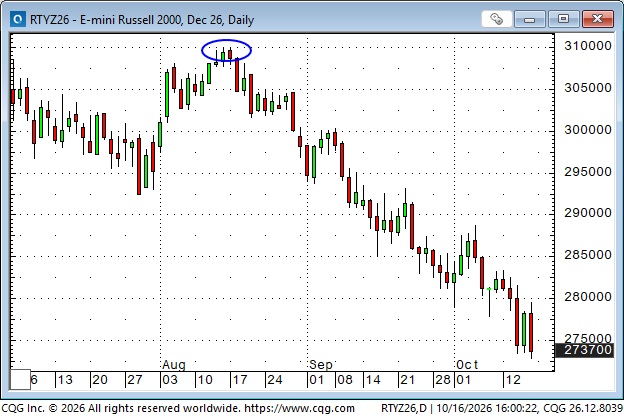
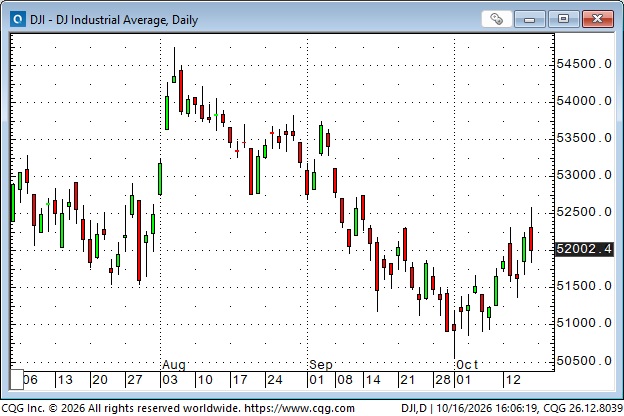
The venerable Dow Jones Industrial Average hit a record high in early August, then lost ~4,000 points (~7%) as it trended lower into October. Still, it has rallied ~2,000 points from those lows while the Nasdaq has been sharply lower. The “stock market” has been anything but “monolithic” since so many indices made highs in mid-August.
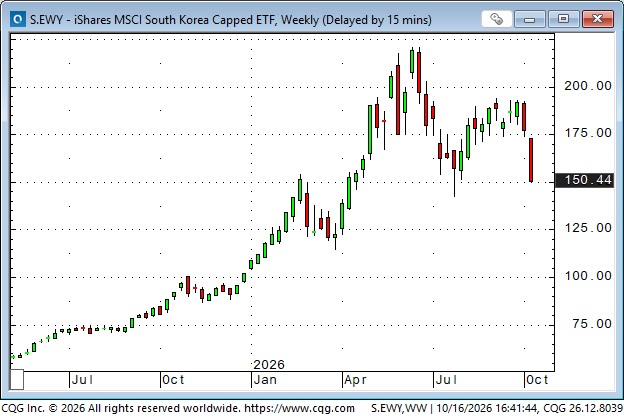
The EWY ETF for the Korean market had a fantastic “run for the roses” on the back of Samsung and SK Hynix, but that’s over now.
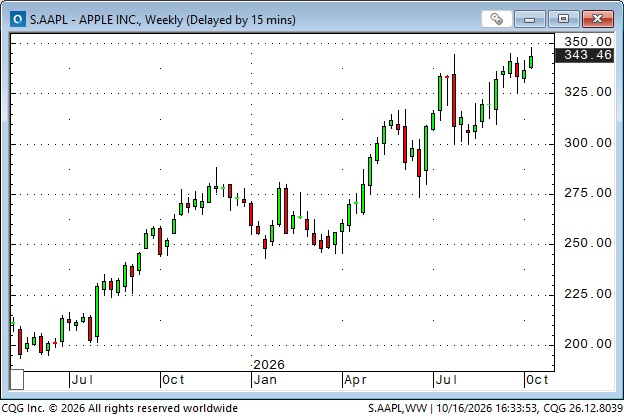
AAPL – The Last Man Standing
On my quote board on Wednesday and again on Friday, tech stocks were a sea of red, with one exception: AAPL. In a note to my friend Stephen Innes (a veteran Canadian trader living in Bangkok – check out his Substack), I said that AAPL looked to be getting “safe haven” flows as other tech stocks fell, and that it would be “Katie bar the door” if AAPL turned red on the week. It didn’t. It closed higher for the week, at a new record-high close.
AAPL is in a class by itself. It has the highest market cap, a history of innovation, and it’s a leading tech company, but it’s not “tainted” by the questions swirling around AI companies. If you’re a money manager and you have to be invested in the tech sector, AAPL looks like a “shelter from the storm.”
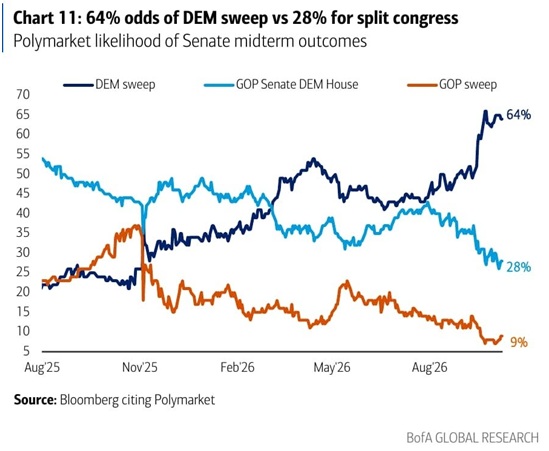
Is the stock market getting the jitters about the midterms?
Energy
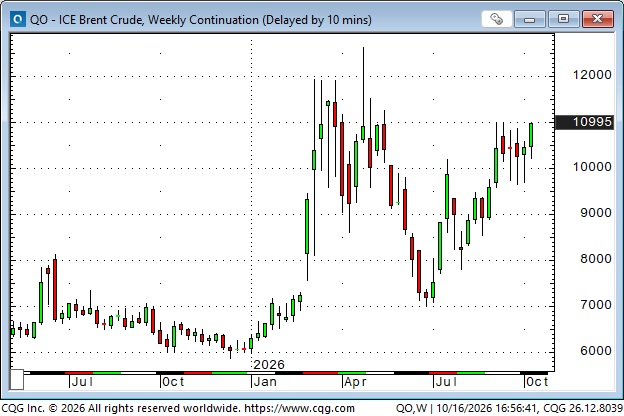
How high is crude oil? Front-month Brent futures closed at $109.95 this week, the highest weekly close we’ve seen this year, except for one week in March.
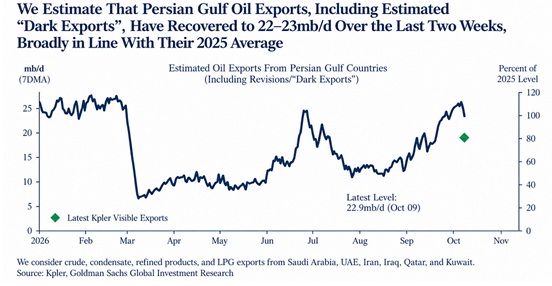
Last week, Goldman estimated daily total crude exports from the Middle East were running “in line” with the 2025 average. With attacks on shipping and the East/West Saudi pipeline this week, those estimates have probably dropped.
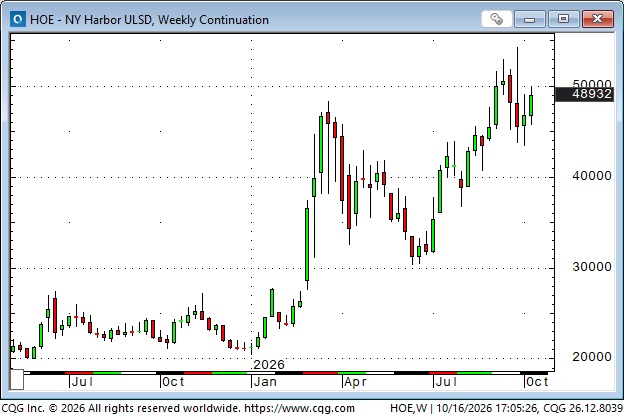
Ultra Low Sulphur Diesel on the NYMEX has remained near recent record highs.
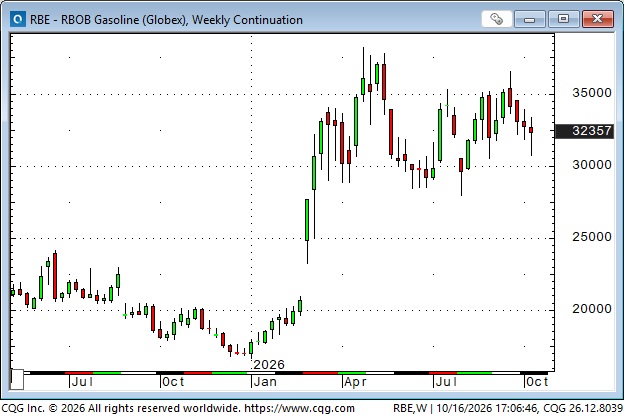
NYMEX gasoline also remains near recent highs.
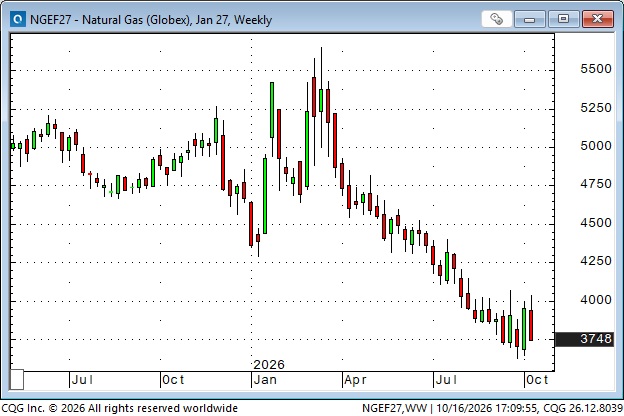
NYMEX natural gas for January (typically the highest-priced month of the year) remains in a steep downtrend.
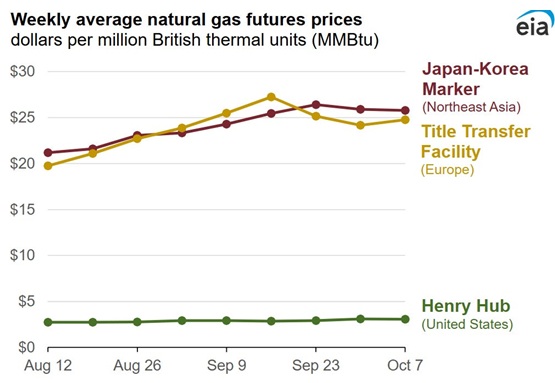
Look at the spread between NYMEX and Asian and European prices.
Metals
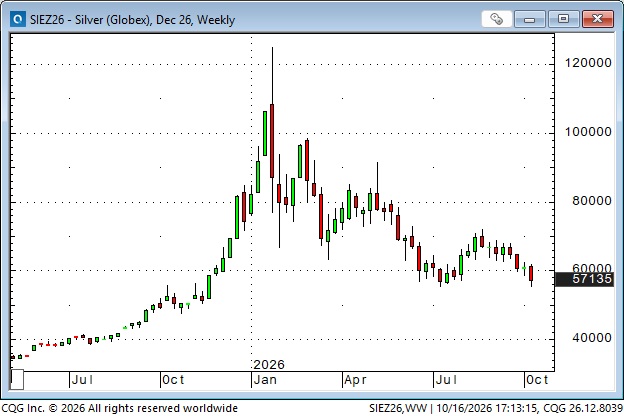
Silver fell to ~$55 this week – down ~ 55% from January’s record highs.
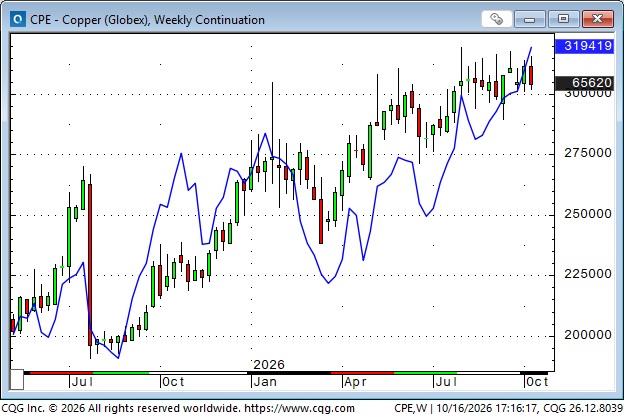
COMEX copper has traded sideways since August, mostly between $6.40 and $6.80. This week’s close was the lowest in 6 weeks. The blue line is open interest. It is up ~30% from the March lows, within a whisker of the all-time highs made in August 2017 when copper was ~$3. A million things contribute to copper’s price. Still, I wonder: if the market develops “2nd thoughts” about AI, will the new longs in this market lose their allegiance to the prevailing bullish copper narrative?
Quote of the week
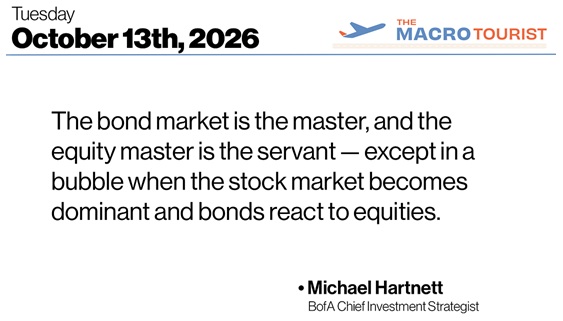
Here’s a link to a great recent video interview with Michael Hartnett.
My short-term trading
I started this week short OTM bond puts and long CAD.
I covered my short bond puts on Wednesday for 2 ticks, for a nice profit. I could have held the trade, and the options would likely expire worthless next week, but the risk/reward isn’t good: a maximum possible gain of 2 ticks versus an unlimited possible loss.
I covered CAD for a small gain ahead of the CPI report and reestablished it after the report when CAD fell. I closed the trade on Friday for a 40-point gain.
I shorted the S&P on Wednesday and covered it on Thursday for a decent win, but missed the big leg down on Friday.
I shorted copper on Wednesday and kept the position into the weekend.
I shorted the Euro on Friday after it rallied over 100 points from Wednesday’s low. I kept the trade into the weekend. My P&L had a good week.
The BC election
I dread the thought of the BC NDP winning the October 24 election, and I have contributed some money to a 3rd party advertiser called Save Our BC.
You can learn more about Save Our BC and contribute on that website.
The Barney report
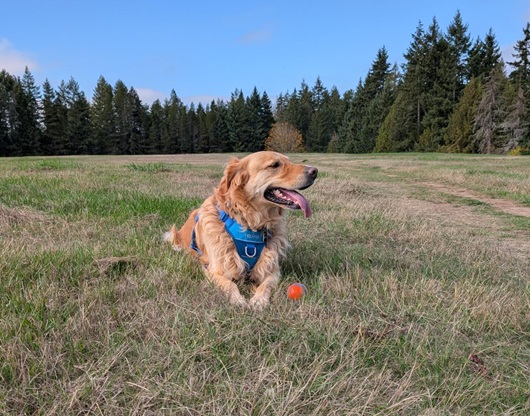
We’ve had some nice weather in October, and Barney and I have made the most of it. His favourite thing, well, outside of running with a stick, is chasing his ball. Here’s a photo of him resting with his ball after 30 minutes of ball-chasing!
Listen to Mike Campbell and me discuss markets
On today’s Moneytalks show, Mike and I talked about the big reversal in the bond market, the “hotter than expected” CPI and PPI reports, and the wild action in the stock market. Listen to the full show here. My spot with Mike starts around the 1-hour, 10-minute mark.
The Archive
Readers can access any of the weekly Trading Desk Notes from the past six years by clicking here.
Subscribe: You have free access to everything on this site. Subscribers receive an email alert when I post new content, typically four to six times a month.
Victor Adair retired from the Canadian brokerage business in 2020 after 44 years and is no longer licensed to provide investment advice. Nothing on this website is investment advice for anyone about anything.