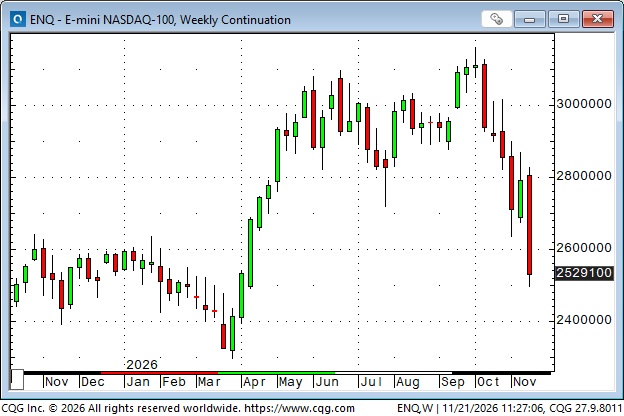
Stocks fell hard this week
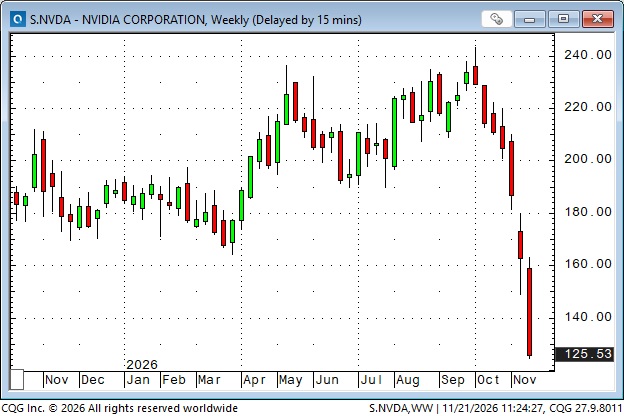
NVDA – Tuesday’s better-than-expected Q report didn’t help.
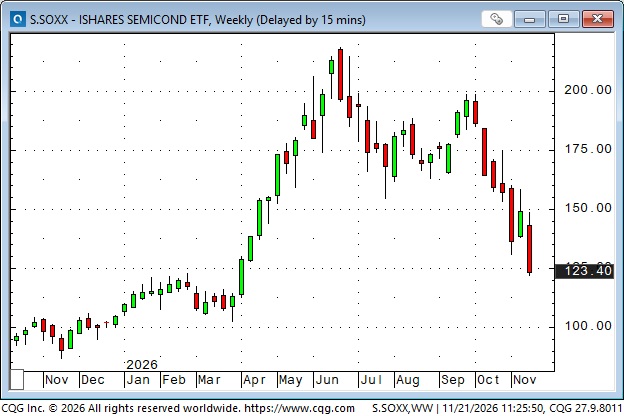
Semiconductor ETF
Nasdaq Index
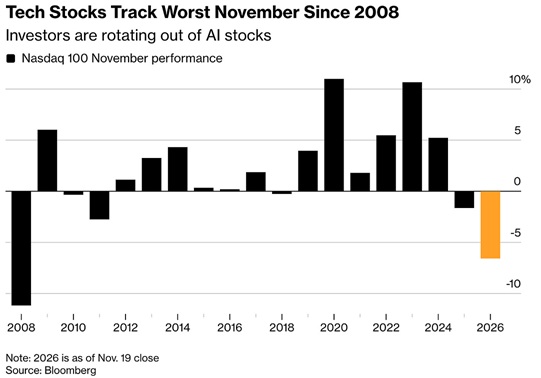
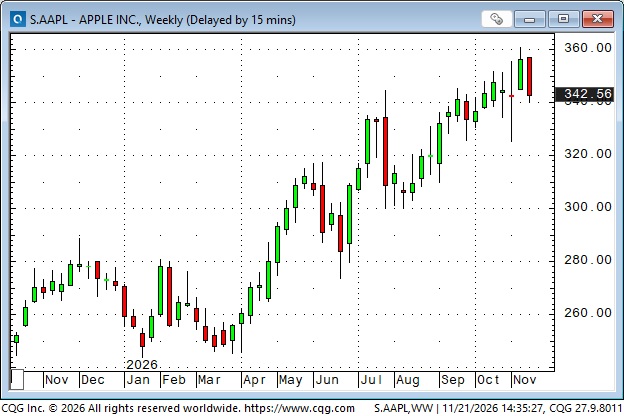
AAPL remains a “refuge” in the tech sector, “untainted” by AI concerns.
S&P 500 Index
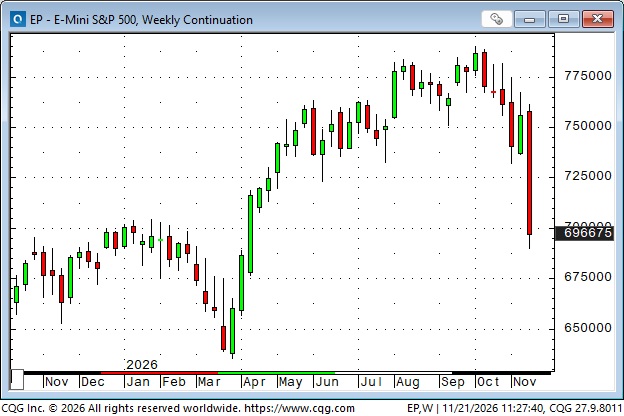
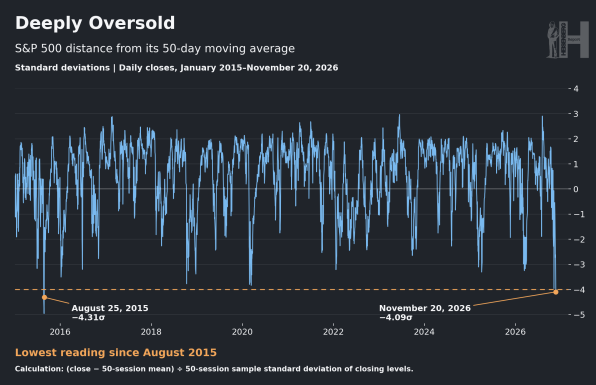
The S&P closed 4 standard deviations below its 50-day moving average on Friday, the lowest in 11 years. This chart is from Heisenberg Report (I’ve been a subscriber for years, and recommend it to my readers). The forward P/E is ~16.5, down from ~22 in January.
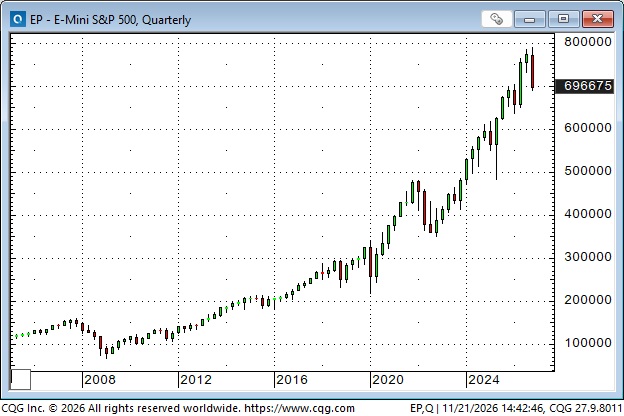
A long-term perspective: the S&P is up ~12X from the March 2009 lows of 666.
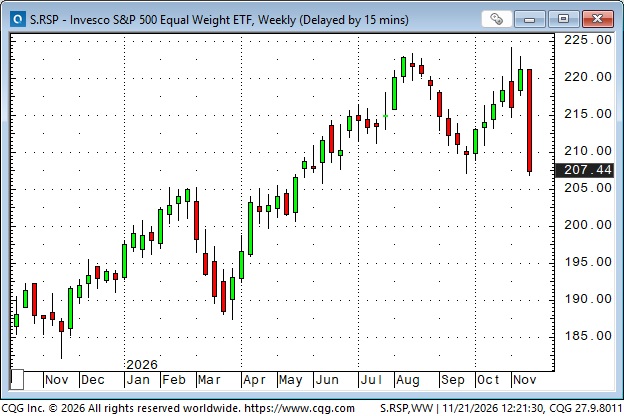
Equal-weight S&P ETF
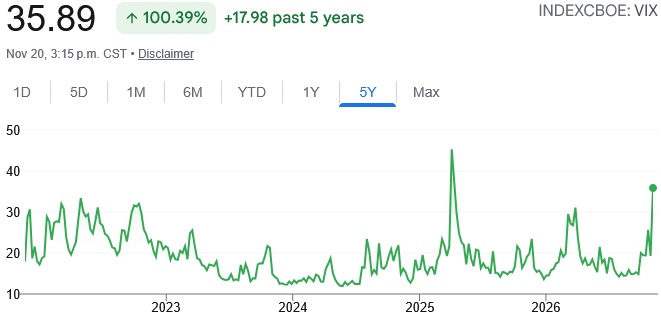
VIX – 19-month high
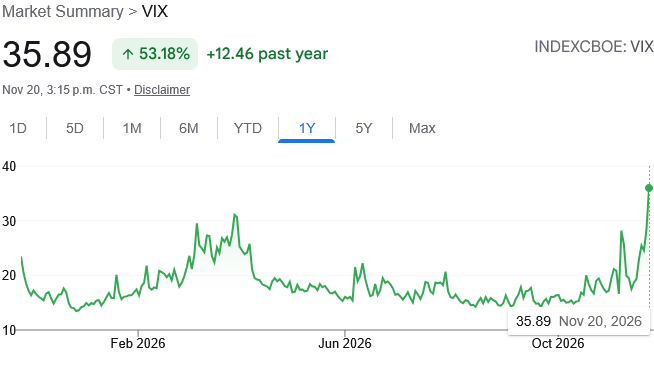
VIX – 5-year lookback
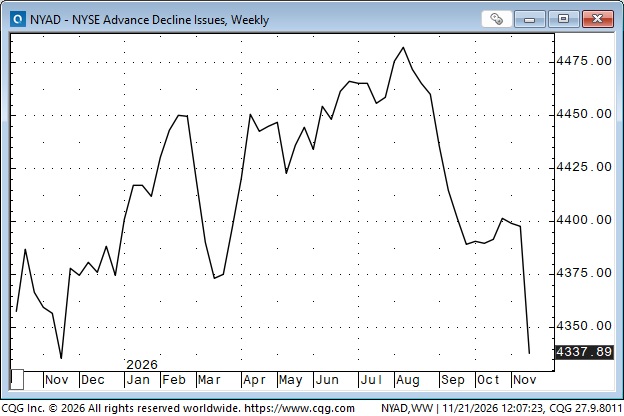
NYSE Advance/Decline Index – 12-month low
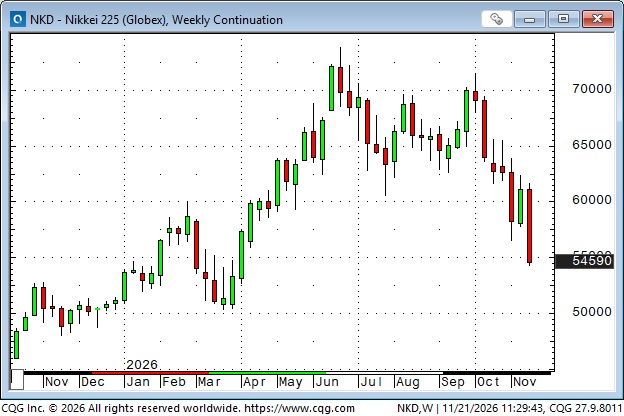
Japanese Nikkei
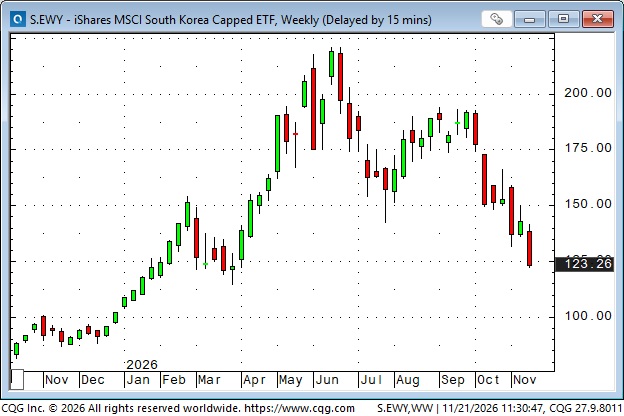
South Korea ETF
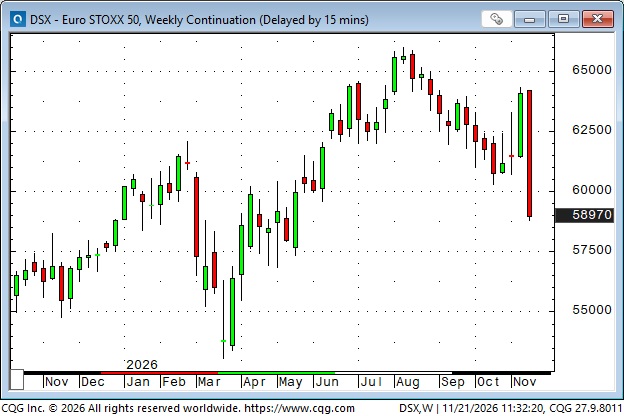
Euro STOXX 50 Index
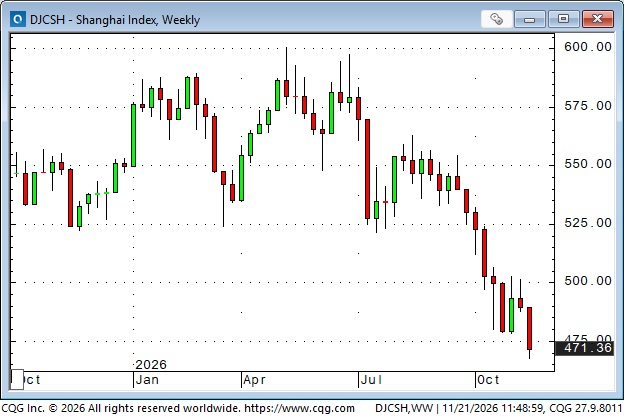
Shanghai Index
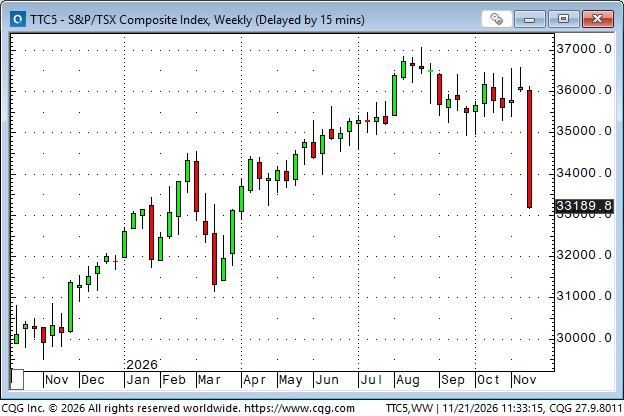
Toronto Composite Index
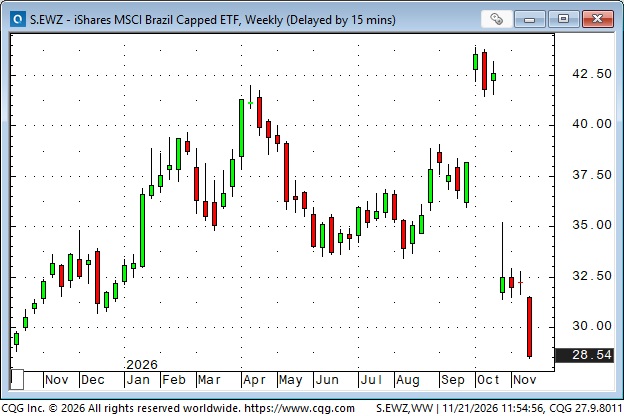
Brazil MSCI ETF
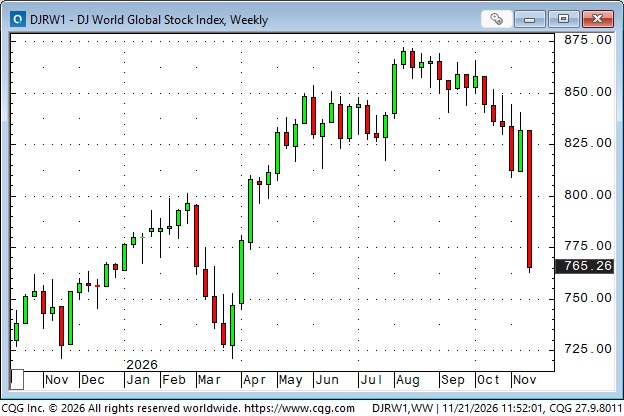
Dow Jones Global Stock Index (cap-weighted, so USA heavy)
Some equities benefited from “rotation” flows:
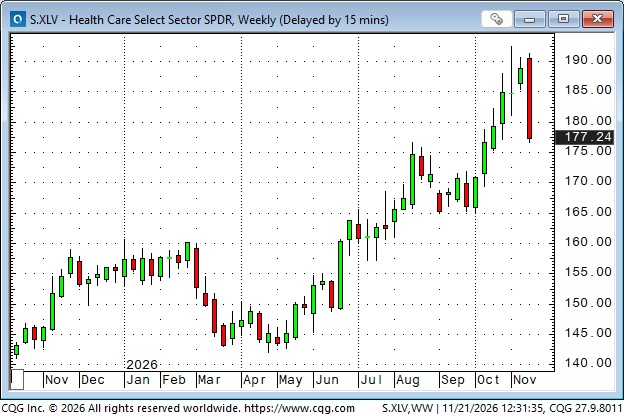
Health Care ETF
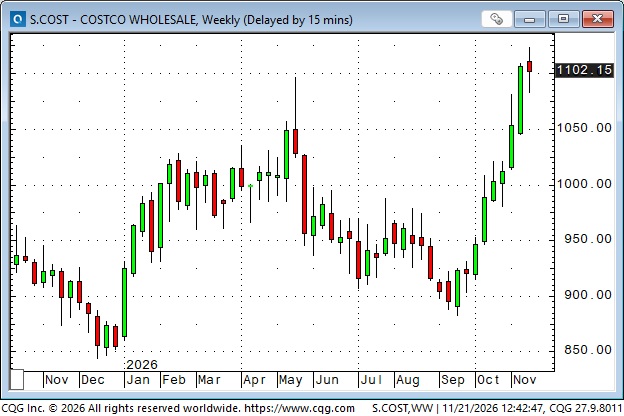
There’s some “dark humor/irony” in Costco surging (up ~20%) to record highs since the beginning of October, while so many other issues were falling. WMT is up ~25% since the beginning of October.
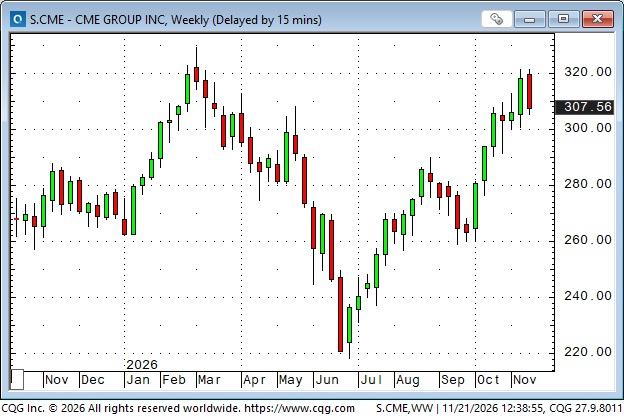
CME shares have surged since early October to near record highs, as futures trading volumes soar.
METALS
Gold – down over $2,000 (~37%) from January’s record highs. Silver is down ~62%.
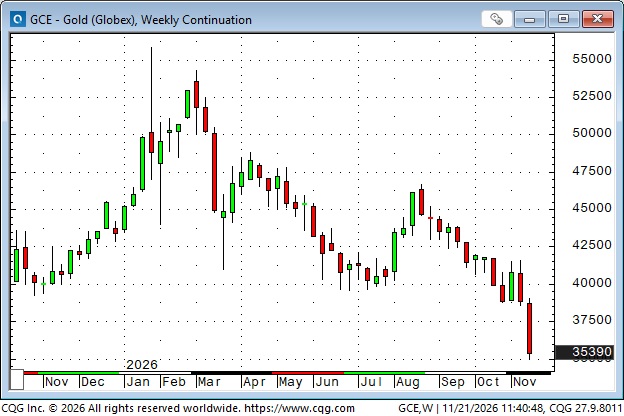
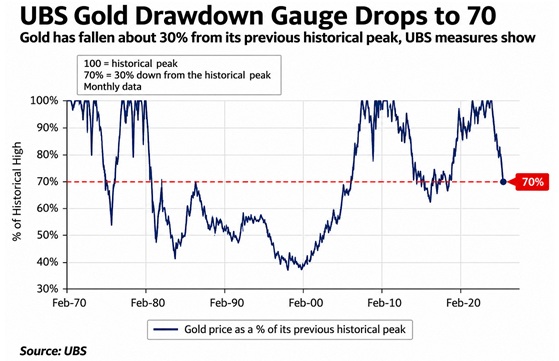
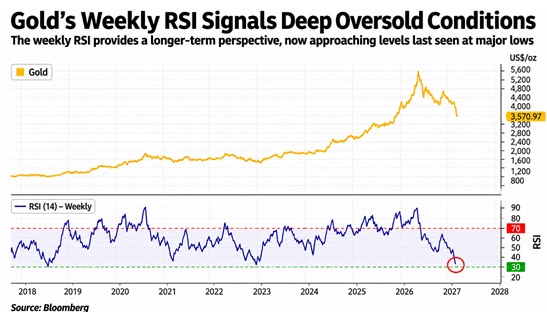
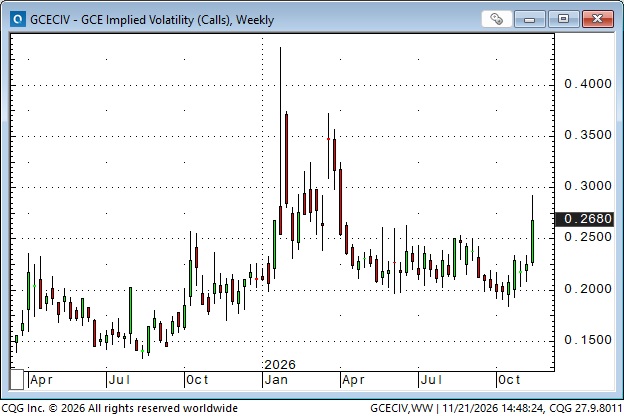
Gold VOL spiked over the past 2 weeks as gold fell ~$650.
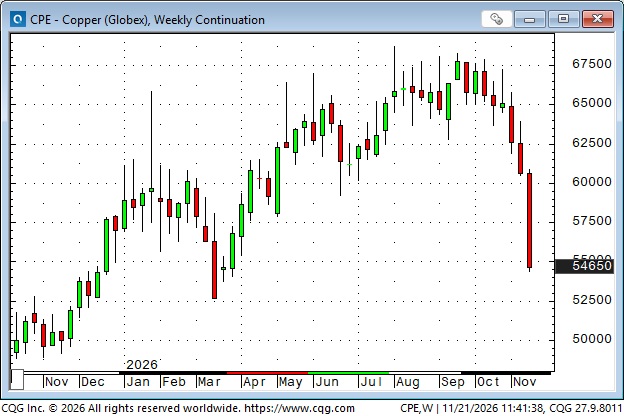
Copper – down over 20% from August’s record highs.
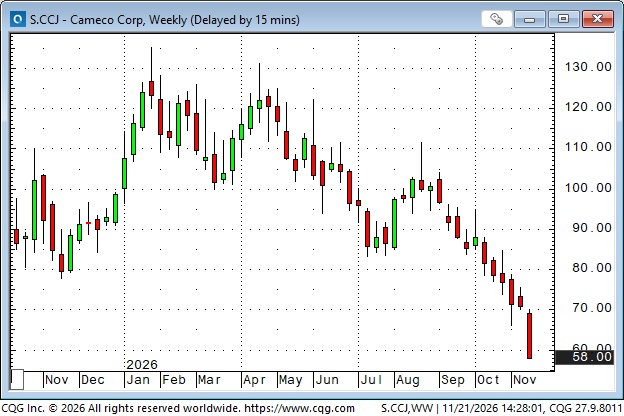
Uranium: Cameco is my “barometer” for the uranium market, and CCJ is down ~57% from its January record highs.
Crypto
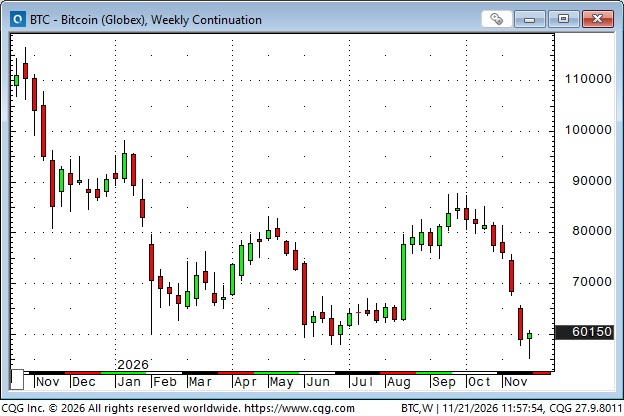
Bitcoin – down ~57% from October 2025 record highs.
Interest rates
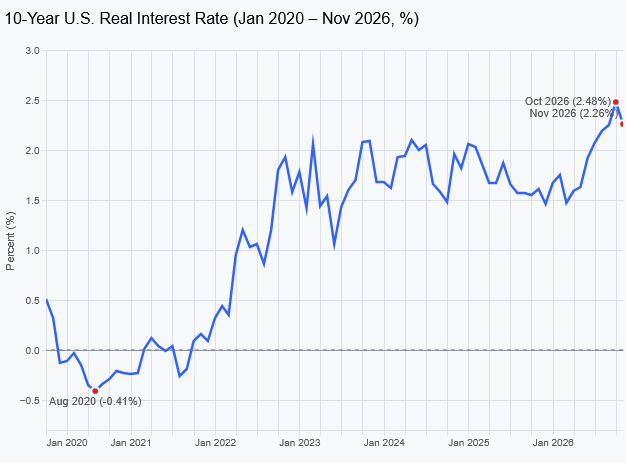
Real yields are at multi-year highs.
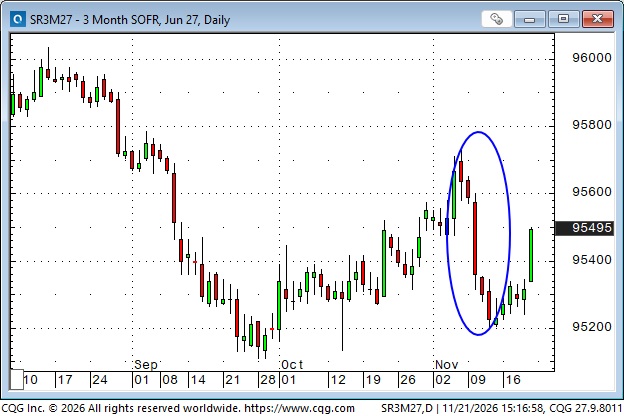
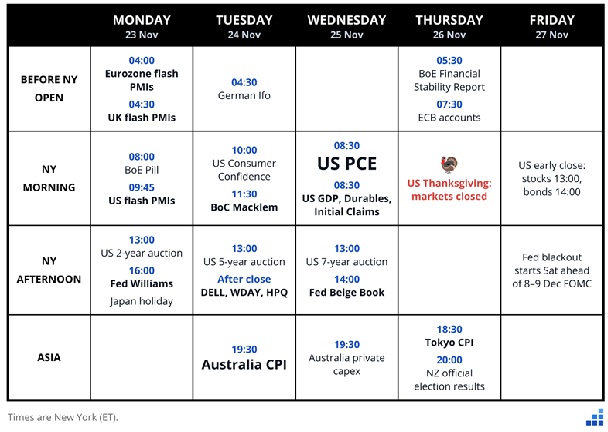
Some FOMC members have been “talking up” interest rates to “get inflation under control.” That, and a hotter-than-expected CPI on November 10, sparked a ~50 bps backup in short rates last week (blue ellipse), but as the stock market losses soared this week, STIR fell. The market is still pricing a 90%+ chance of a 25 bps hike at the December 9 FOMC meeting. The headline PCE data this coming Wednesday is expected to rise 0.3% MoM and 3.8% YoY, with core up 0.3% MoM and 3.3% YoY. The next CPI report is on December 10, one day after the next FOMC meeting.
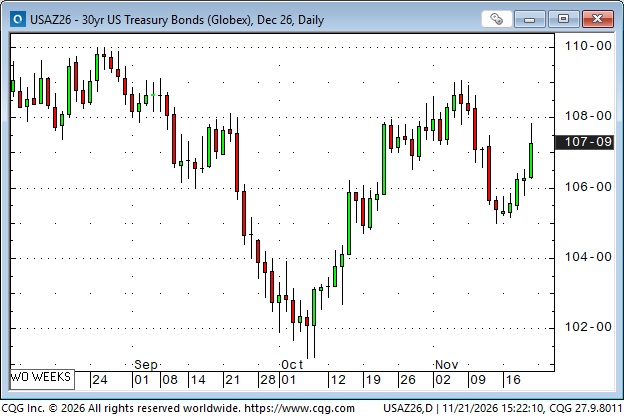
Over the last 2 weeks, the bond market showed a pattern similar to STIR. Friday’s strong bond rally looked like a direct response to the sharp declines in the stock market.
Currencies
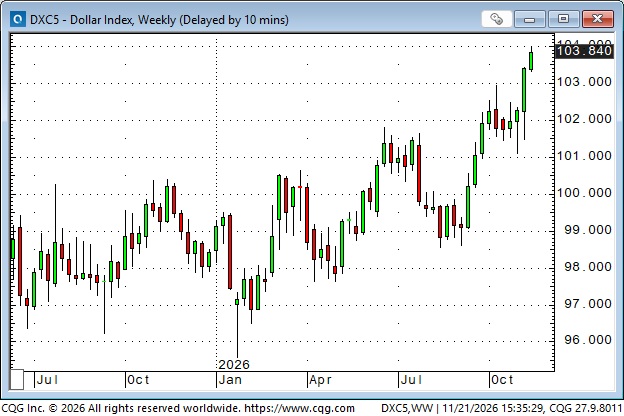
The DXY US Dollar Index rose to a 20-month high this week. Interest rate differentials have helped the USD rise, but massive foreign capital flows into US securities may have been the “driving force” behind the USD’s rise.
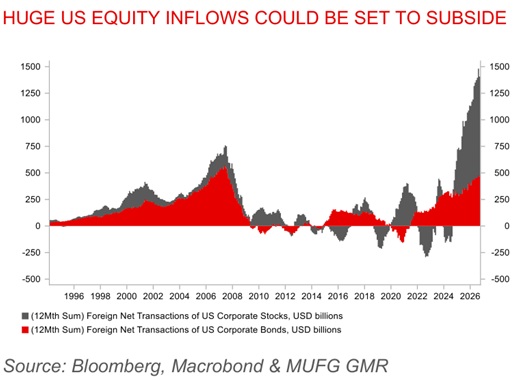
These foreign capital flows raise the question: “Will the USD weaken if US equity markets continue to fall?” (Foreigners could sell USD to hedge their holdings, or sell their holdings and repatriate their capital.)
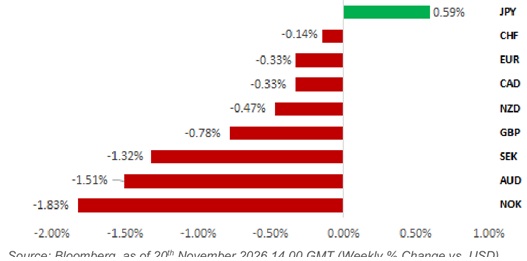
This week’s price action against the USD.
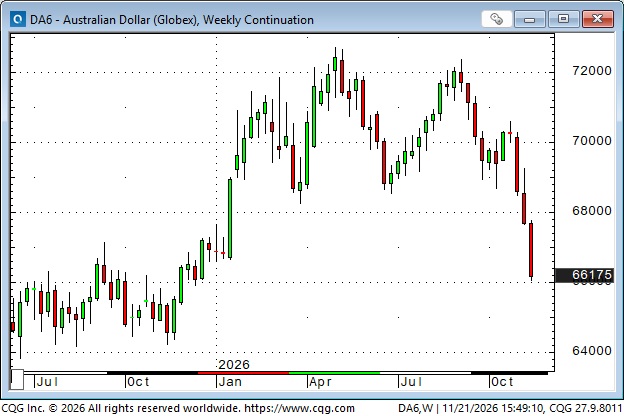
Speculators in the currency futures market have been building a record-sized net short position in the Australian Dollar over the last 7 weeks. 12-month forward STIR expectations are +65 bps for the USD and -35 bps for the AUD.
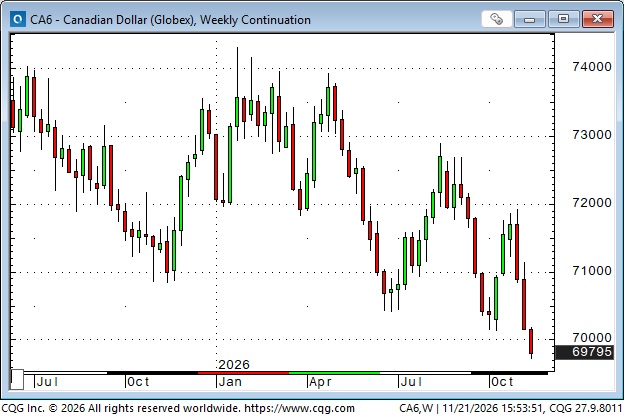
The Canadian Dollar is below 70 cents for the first time in 20 months. 12-month forward STIR expectations are +65 bps for both the CAD and the USD.
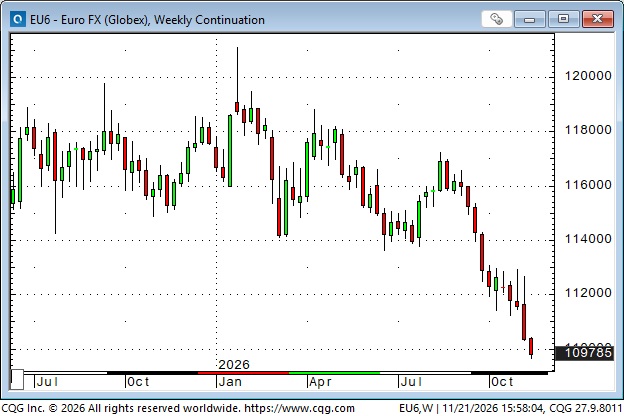
Speculators in the currency futures market have built a net short position in the Euro that is the largest in ~10 years.
Energy
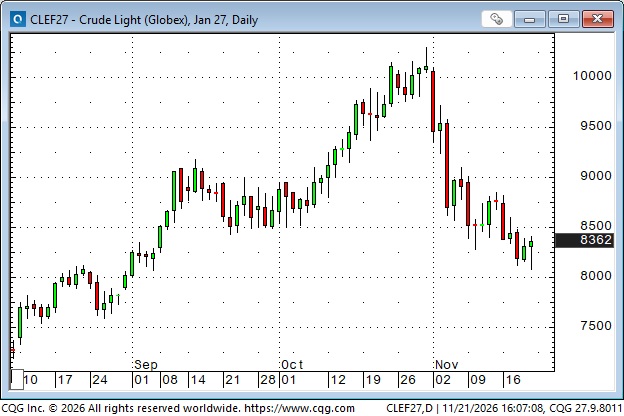
NYMEX January WTI fell over 20% from recent highs to this week’s lows as Middle East oil exports rose (despite Iran attacking some shipping) and markets tentatively priced in a de-escalation of the war. However, prices rallied on Friday, perhaps “just in case” military activity ramped up over the weekend. American crude oil production hit another record high, and the IEA sees global crude supply greater than demand in Q4 by ~1.7 mbpd.
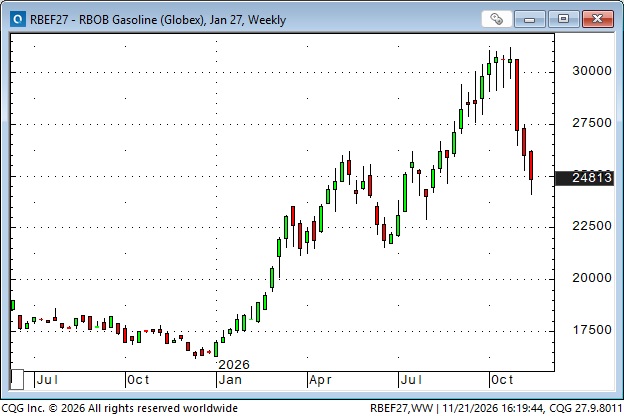
NYMEX heating oil and gasoline prices have declined in November, although not as much as crude oil prices.
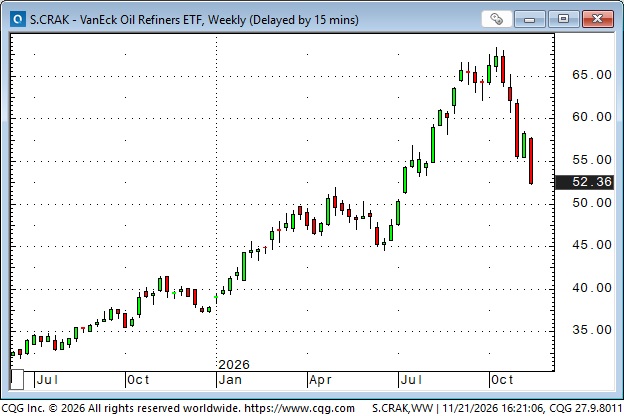
Crack spreads fell, and refiner share prices fell.
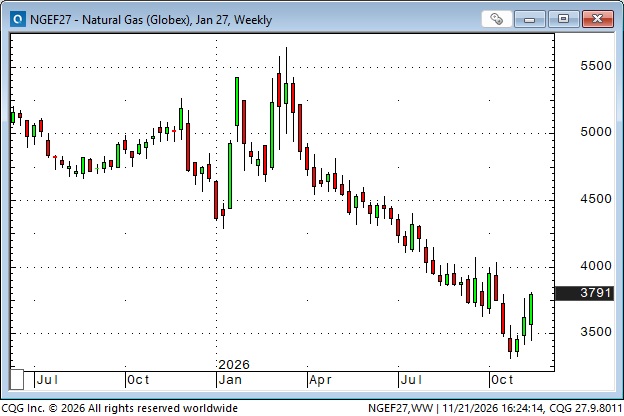
NYMEX January natural gas prices have rallied over the past 3 weeks after a huge decline since the war with Iran started. Speculators have maintained a massive record-sized net short position.
What do I really think?
I’ve been trading for over 50 years, and I thought that speculative excesses had taken markets (especially stocks, precious metals and crypto) WAY TOO HIGH. I think we’re seeing some de-leveraging, de-risking, and margin-call selling. It could continue. When any market is WAY TOO HIGH, almost anything can trigger a reversal, and as prices fall, selling begets more selling. I think the global appetite for leveraged risk is deteriorating. Some people have experienced a tremendous rise in their net worth from sharply rising share prices, and they think that’s “normal,” and (at least the ones that are not WAY overleveraged) they are probably getting ready to “buy the dip.”
This calendar is from Brent Donnelly.
My short-term trading
I bought the dip in the S&P three times on Monday, and lost a little money each time. Thankfully, I have little patience with a losing trade, and I use tight stops.
I bought 10-year T-Note futures on Wednesday and held that trade into the weekend as the market rallied sharply while stocks fell.
My net realized and unrealized P&L for the week was nicely in the black.
The Barney report
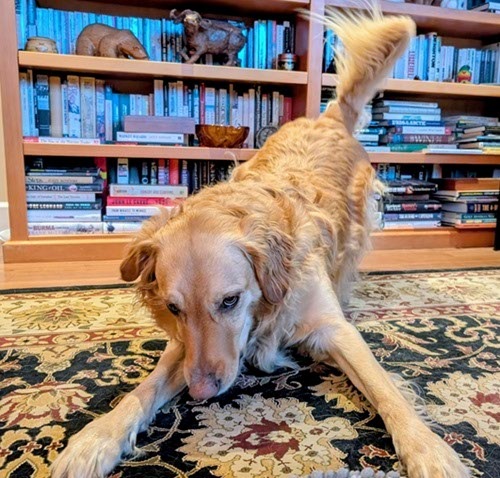
My wife has been away this week (visiting 16-month-old twin granddaughters!), and Barney and I have been “home alone” together. He usually sticks pretty close to me when it’s just the two of us here, and now he is trying to get me to stop writing this report and play with him.
Listen to Mike Campbell and me discuss markets
On this week’s Moneytalks show, Mike and I focused on the “drama” in the stock and gold markets. We also discussed copper, currencies and interest rates. You can listen to the entire show here. My spot with Mike starts around the 42-minute mark. Be sure to listen to Tony Greer, our featured guest this week. His spot starts around the 5-minute mark. Tony will be one of our key speakers at the 2027 World Outlook Conference.
I will be hosting the Moneytalks show for the next two weeks while Mike is on a well-deserved vacation. My featured guest next week is Kevin Muir, and the following week, Brent Donnelly will join me.
The 38th Annual World Outlook Financial Conference
Mike and his team will host another great conference at the Bayshore Hotel in Vancouver on February 5 and 6, 2027. I will be the opening speaker on Friday afternoon and will help Mike with MC duties on Saturday. I look forward to meeting many of my subscribers at the conference. Please don’t be shy to say hello.
The conference has a terrific lineup of speakers and presenters; click here to access all the information you need and to register to attend.
The Archive
Readers can access any of the weekly Trading Desk Notes from the past six years by clicking here.
Subscribe: You have free access to everything on this site. Subscribers receive an email alert when I post new content, typically four to six times a month.
Victor Adair retired from the Canadian brokerage business in 2020 after 44 years and is no longer licensed to provide investment advice. Nothing on this website is investment advice for anyone about anything.